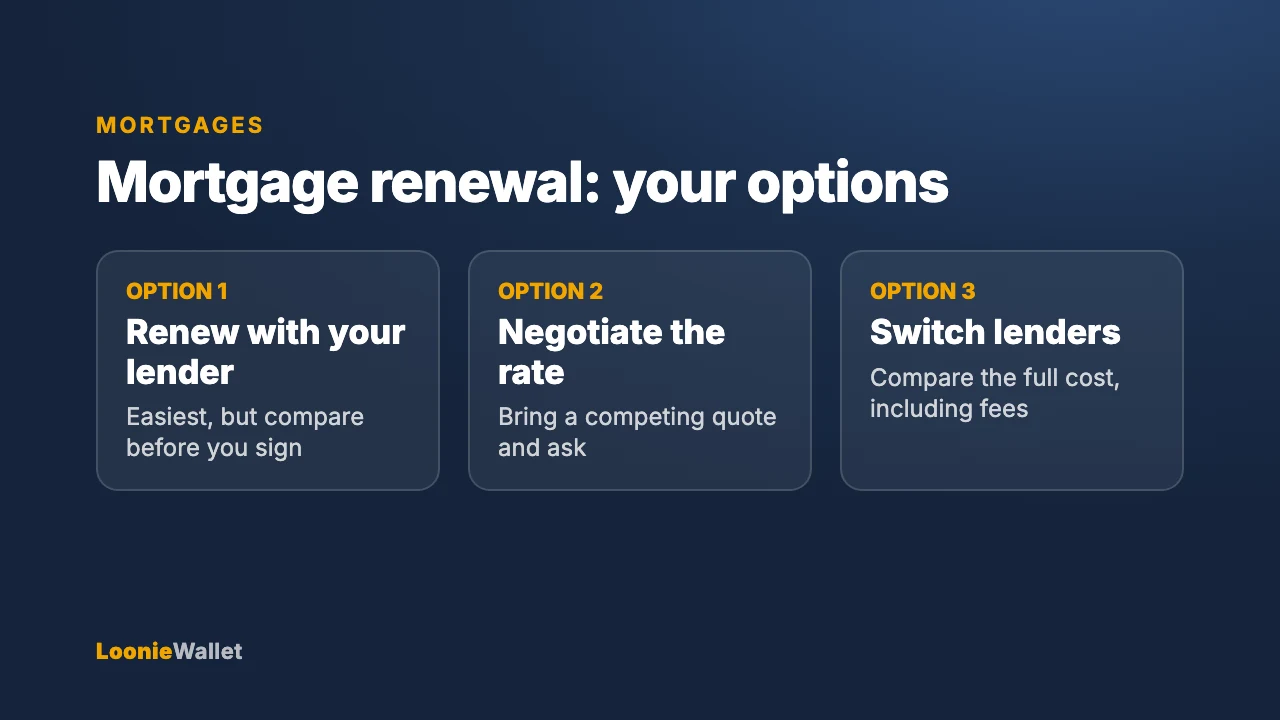
Mortgage Renewal in Canada: The 2026 Checklist and Payment Comparison
Renewing a mortgage in 2026? Here is what your payment does at today's rates, when you can switch lenders without requalifying, what a switch costs, and a 120-day checklist.
Renewing a mortgage in 2026? Here is what your payment does at today's rates, when you can switch lenders without requalifying, what a switch costs, and a 120-day checklist.
How the First Home Savings Account works in 2026: who qualifies, the $8,000 and $40,000 limits, how the deduction works, the exact conditions for a tax-free withdrawal, and your options if you never buy.

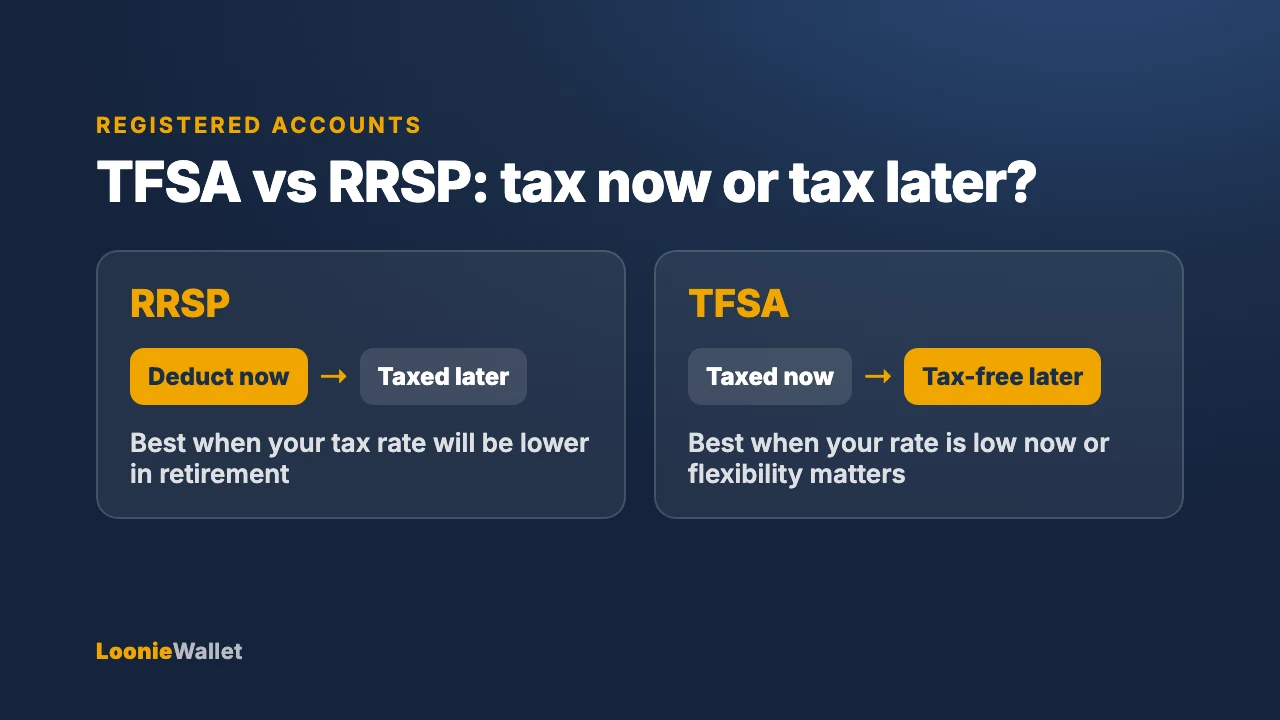
One rule decides it: your tax rate today versus your tax rate when you withdraw. Here is that rule with 2026 numbers for every income level, the two exceptions that override it, and a calculator for your own case.

The order to fill the three accounts, a calendar of the deadlines that trip people up, and two worked examples: a single buyer with five years and a couple buying in eighteen months. Then a check against the minimum down payment and the insured cap.

A five-year fixed costs more than a variable today. Whether it is worth it depends on how much a rate rise would hurt you, not on a forecast. Three rate paths, the short-fixed alternative most borrowers are now choosing, trigger rates, and the penalty gap, all with numbers.

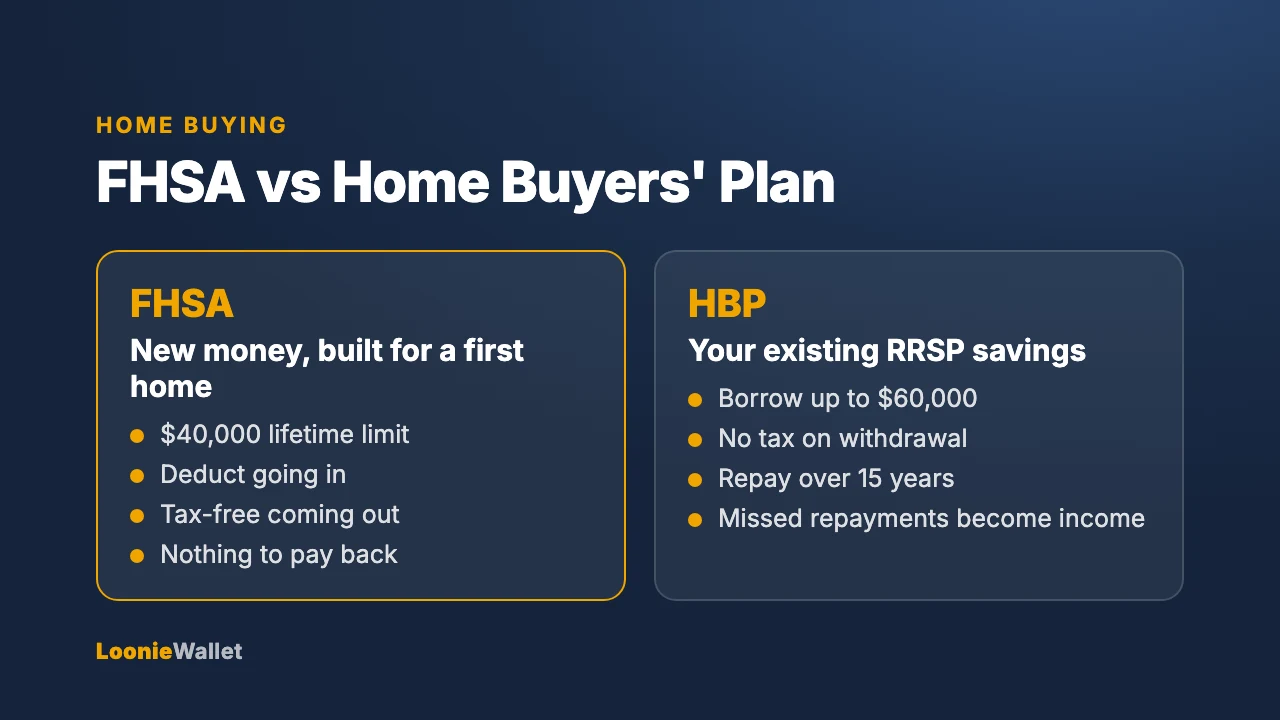
Both give you a deduction and a tax-free withdrawal for a first home. One has to be paid back over 15 years. Here is how the two compare, the exact conditions for each, the repayment schedule under the 2022–2028 deferral, and how to stack them.